Insurance can leave eligible expenses unpaid. An HSA gives your team a flexible allowance to help cover that gap. Compare what each option pays for, the protection you need to keep, and the total cost to your business.
Bring your current insurance costs, employee count and benefit budget. Aya can prepare a quote for the account and funding approach you are considering. Compare the benefits, fees and coverage you would retain before making a change.
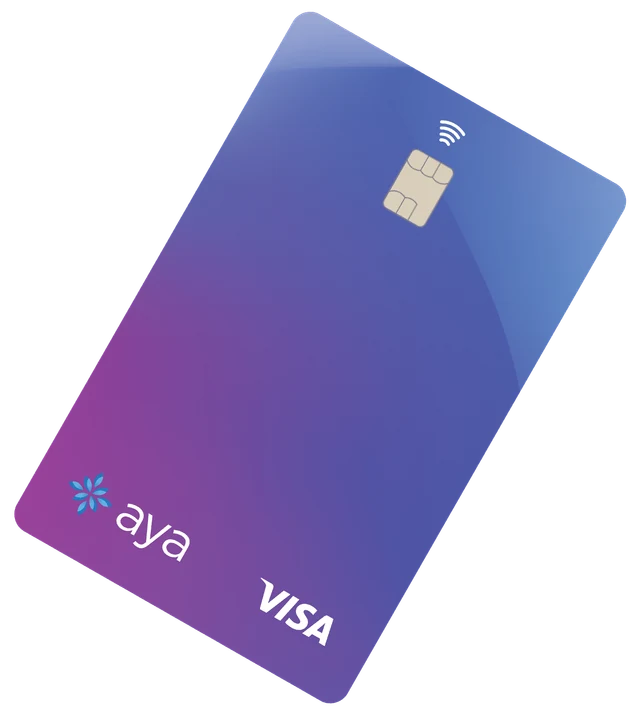
Pay for eligible care with your funded Aya card at designated merchants that accept Visa, including internationally.
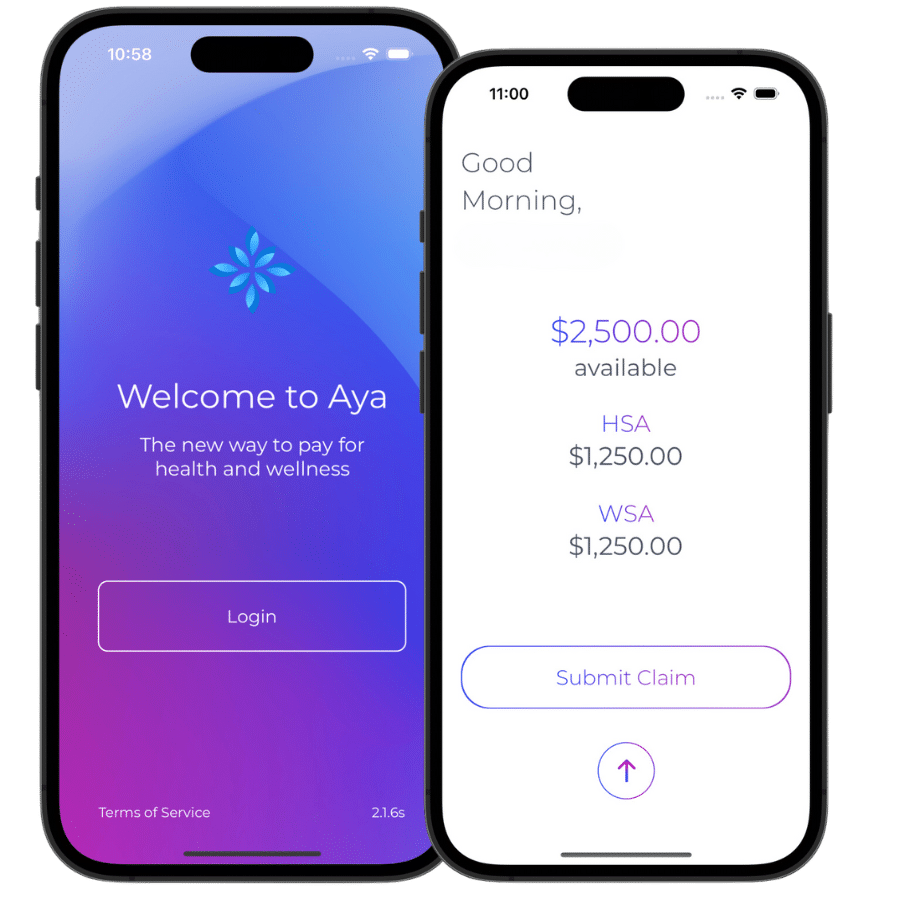
Use your benefit funds at checkout. An approved card payment uses your available plan balance, so you do not need to pay personally and wait for reimbursement.
Pay in person, online or by phone. Use the payment method that fits the eligible provider.
Manage the card in the app. View your account and lock your card when needed.
Available funds, eligible expenses, merchant restrictions and the cardholder agreement apply. Keep and upload your receipts. International card acceptance is separate from travel medical insurance.
Set HSA and WSA allocations for defined employee classes, including executives. Give people choice within their allowance, with a funded card for eligible care in Canada and abroad.
Use objective class criteria and consistent allocations within each class. Build the plan around the roles and needs of your team.
A qualifying HSA lets your company pay eligible healthcare expenses as an employee benefit. Qualifying employer costs are deductible business expenses; eligible benefits are non-taxable federally.
Owner-managers who are employees of incorporated businesses can participate. The benefit must be provided in their capacity as an employee, with a properly structured plan.
Québec provincial tax treatment differs. Confirm your company’s eligibility and deductions with your accountant. Federal health-benefit tax treatment.
HSA or insurance: where is the tax advantage?
Both can qualify for favourable health-benefit tax treatment. Aya’s HSA adds flexible spending within an employer-set budget. A WSA expands the benefits you can offer, with taxable employee benefits.
PUTTING YOUR PLAN TO USE
Your next questions, answered.
What if we already have a provider?+
No problem! Eligible expenses go to the primary group benefits plan first, then to a partner’s plan if applicable. Any unpaid portions can then be submitted to Aya’s HSA/WSA for comprehensive coverage.
Only the eligible unpaid amount can be claimed through Aya, within the employee’s available balance. Keep the other insurer’s claim statement.
Can an HSA help me use retained company earnings for healthcare?+
Yes, an eligible corporation can use company funds to provide qualifying healthcare benefits to an owner-manager who is an employee. This pays eligible health expenses through an employment benefit; it is not an unrestricted tax-free withdrawal of retained earnings.
The rules differ. A sole proprietor with no arm’s-length employees does not qualify for an HSA deduction under the CRA’s stated guidance. Incorporated businesses, including eligible shareholder-employees, can participate. Read the CRA’s HSA guidance.
YOUR PLAN STARTS HERE
Build the right mix for your company.
Bring your renewal quote, employee count and benefit priorities. We’ll help you compare spending-account options and confirm your plan and pricing.